


Digital Currency Remittances Gain Traction In Nigeria
TLDR
- Nigeria is a leading market for digital currency remittances, accounting for 60% of Sub-Saharan Africa's stablecoin inflows since 2019.
- The shift is driven by high fees and slow processing times of traditional channels, with digital options costing significantly less.
- Infrastructure providers are addressing the "last mile" challenge of converting stablecoins to local currency, with regulators monitoring the sector.
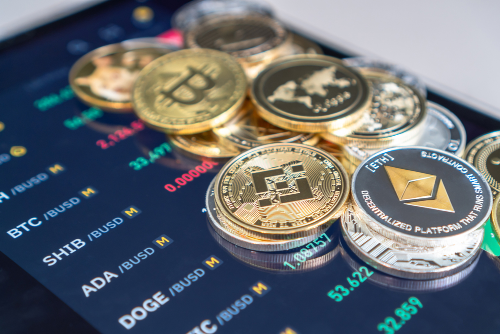
Nigeria has emerged as a significant market for digital currency remittances, with the International Monetary Fund (IMF) estimating the country accounted for approximately 60% of Sub-Saharan Africa’s stablecoin inflows since 2019. This growth highlights a strong demand for alternative money transfer methods, even before dedicated products were widely available. Regulators, including the Central Bank of Nigeria (CBN) and the Securities and Exchange Commission (SEC), are closely monitoring the sector. Mastercard and Busha recently launched a solution to simplify transfers, while infrastructure providers like Breet are addressing payout challenges.
Digital currency remittances involve converting funds into a dollar-linked stablecoin, sending it to a recipient's wallet, and then cashing out to local currency like naira or cedis. This method bypasses traditional correspondent banking chains, which are often slow and costly. While wallet-to-wallet stablecoin transfers are quick and inexpensive, the critical "last mile" step of converting stablecoins into spendable local currency remains a challenge. This final conversion often faces issues such as bank account flagging and fluctuating exchange rates.
Nigeria ranked third globally on Chainalysis’s 2026 Global Crypto Adoption Index, leading in both P2P and cross-border flows. The country's value received from digital currencies rose to over $92.1 billion between July 2024 and June 2025. Traditional remittances to Nigeria are also substantial, with the CBN expecting diaspora remittances to reach about $1 billion a month by the end of 2026. The cost difference is significant: sending $200 to Sub-Saharan Africa averaged 8.46% in Q3 2025 via traditional channels, compared to 0.5% to 2% for stablecoin payment gateways.
The shift to digital remittances is driven by high fees, long waiting times, and limited access to foreign exchange through traditional channels. For instance, a $200 transfer to Sub-Saharan Africa can incur about $17 in traditional fees. Stablecoins offer a hedge against naira depreciation and inflation, attracting users seeking dollar-linked assets. This trend creates opportunities for companies like Breet, which provides automated settlement infrastructure, enabling businesses to convert stablecoins to local currency quickly and compliantly.
The IMF's June 2026 report highlighted the risk of "digital dollarization," where increased stablecoin holdings could reduce demand for the naira and impact monetary policy. However, the report suggests this shift is unlikely to reverse. Nigeria's ISA 2025 now places virtual asset service providers under SEC oversight, requiring registration and enhancing monitoring. Solutions like Breet's API, which has processed over 3 million programmatic transactions, aim to provide compliant and efficient settlement, addressing the remaining challenges in the digital remittance ecosystem.
Key Takeaways
Think someone else should see this?
To invest in this opportunity and other opportunities across Africa
Download the daba finance app on your mobile through

Take action.

Download app

Partner with us
Unlock exciting business opportunities and growth potential.
Join Daba
Become a part of our vibrant community and enjoy exclusive benefits.
Contact us
Reach out to us for inquiries, support, or collaboration.